

Running a dump truck operation in California means carrying real financial exposure every time your wheels hit the road. Between state-mandated liability minimums, FMCSA filing requirements, and the constant threat of nuclear verdicts, your insurance program isn't just a line item: it's the backbone of your business continuity. California dump truck and construction hauling insurance covers a range of protections, from fleet auto liability and physical damage to motor truck cargo, hired and non-owned auto coverage, and required federal filings. Getting any one of these wrong can shut down your operation overnight. The stakes have only grown sharper since the AB5 exemption for construction trucking providers expired on December 31, 2024, making worker classification under the ABC test fully mandatory. That change ripples directly into how your policies are structured and who's covered under them. Whether you're running a single ten-wheeler or managing a fleet of transfer dumps across Southern California, understanding each coverage layer is the difference between surviving a claim and closing your doors.
California imposes some of the strictest insurance requirements on commercial haulers in the country. The regulatory framework involves both state agencies (CPUC, Caltrans, DMV) and federal oversight through the FMCSA, and you need to satisfy all of them simultaneously. Missing a single filing or letting a permit lapse doesn't just trigger fines: it can pull your authority to operate.
Minimum Liability and MCP Requirements
If you're hauling property for hire in California, you need a Motor Carrier Permit (MCP) from the DMV. That permit comes with mandatory liability insurance minimums, which vary based on your gross vehicle weight and what you're carrying. California for-hire property carriers with a GVWR of 10,001 lbs or more must maintain a minimum of $750,000 in liability insurance filed via Form MC 65 M (https://www.socaltruckins.com/what-truck-insurance-is-legally-required-in-california/). While the state minimum is $750,000, most California construction contracts and brokers require a $1 million Combined Single Limit (CSL) for site access, and bulk petroleum transporters are required to carry $1.2 million (https://www.haulhandbook.com/california/trucking-insurance-requirements/).
The FMCSA has issued a proposed rulemaking in late 2026 that could raise federal liability minimums from $750,000 to $2 million or more for interstate haulers. Even if you only run intrastate loads, California often mirrors federal increases. Smart operators are already building higher limits into their programs to avoid scrambling later.
The Role of CA Numbers and DOT Filings
Every for-hire carrier in California needs a CA number from the CPUC, and interstate operators need a USDOT number from the FMCSA. Your insurance carrier must file proof of coverage directly with these agencies: Form E for liability, Form H for cargo. If your insurer cancels or non-renews your policy, they're required to notify the agencies, which triggers an automatic suspension of your authority.
Keeping your filings current isn't optional. A lapsed filing means you're operating illegally, and if you're involved in an accident during that gap, you're personally exposed for the full amount of any judgment. We've seen operators at Fusco Orsini & Associates lose everything because a filing lapsed during a carrier switch and nobody caught it for 30 days.
Core Coverages for Dump Truck Operators
Your insurance program needs multiple layers working together. No single policy covers every risk a dump truck operation faces, and gaps between coverages are where claims destroy businesses.
Physical Damage and Cargo Protection
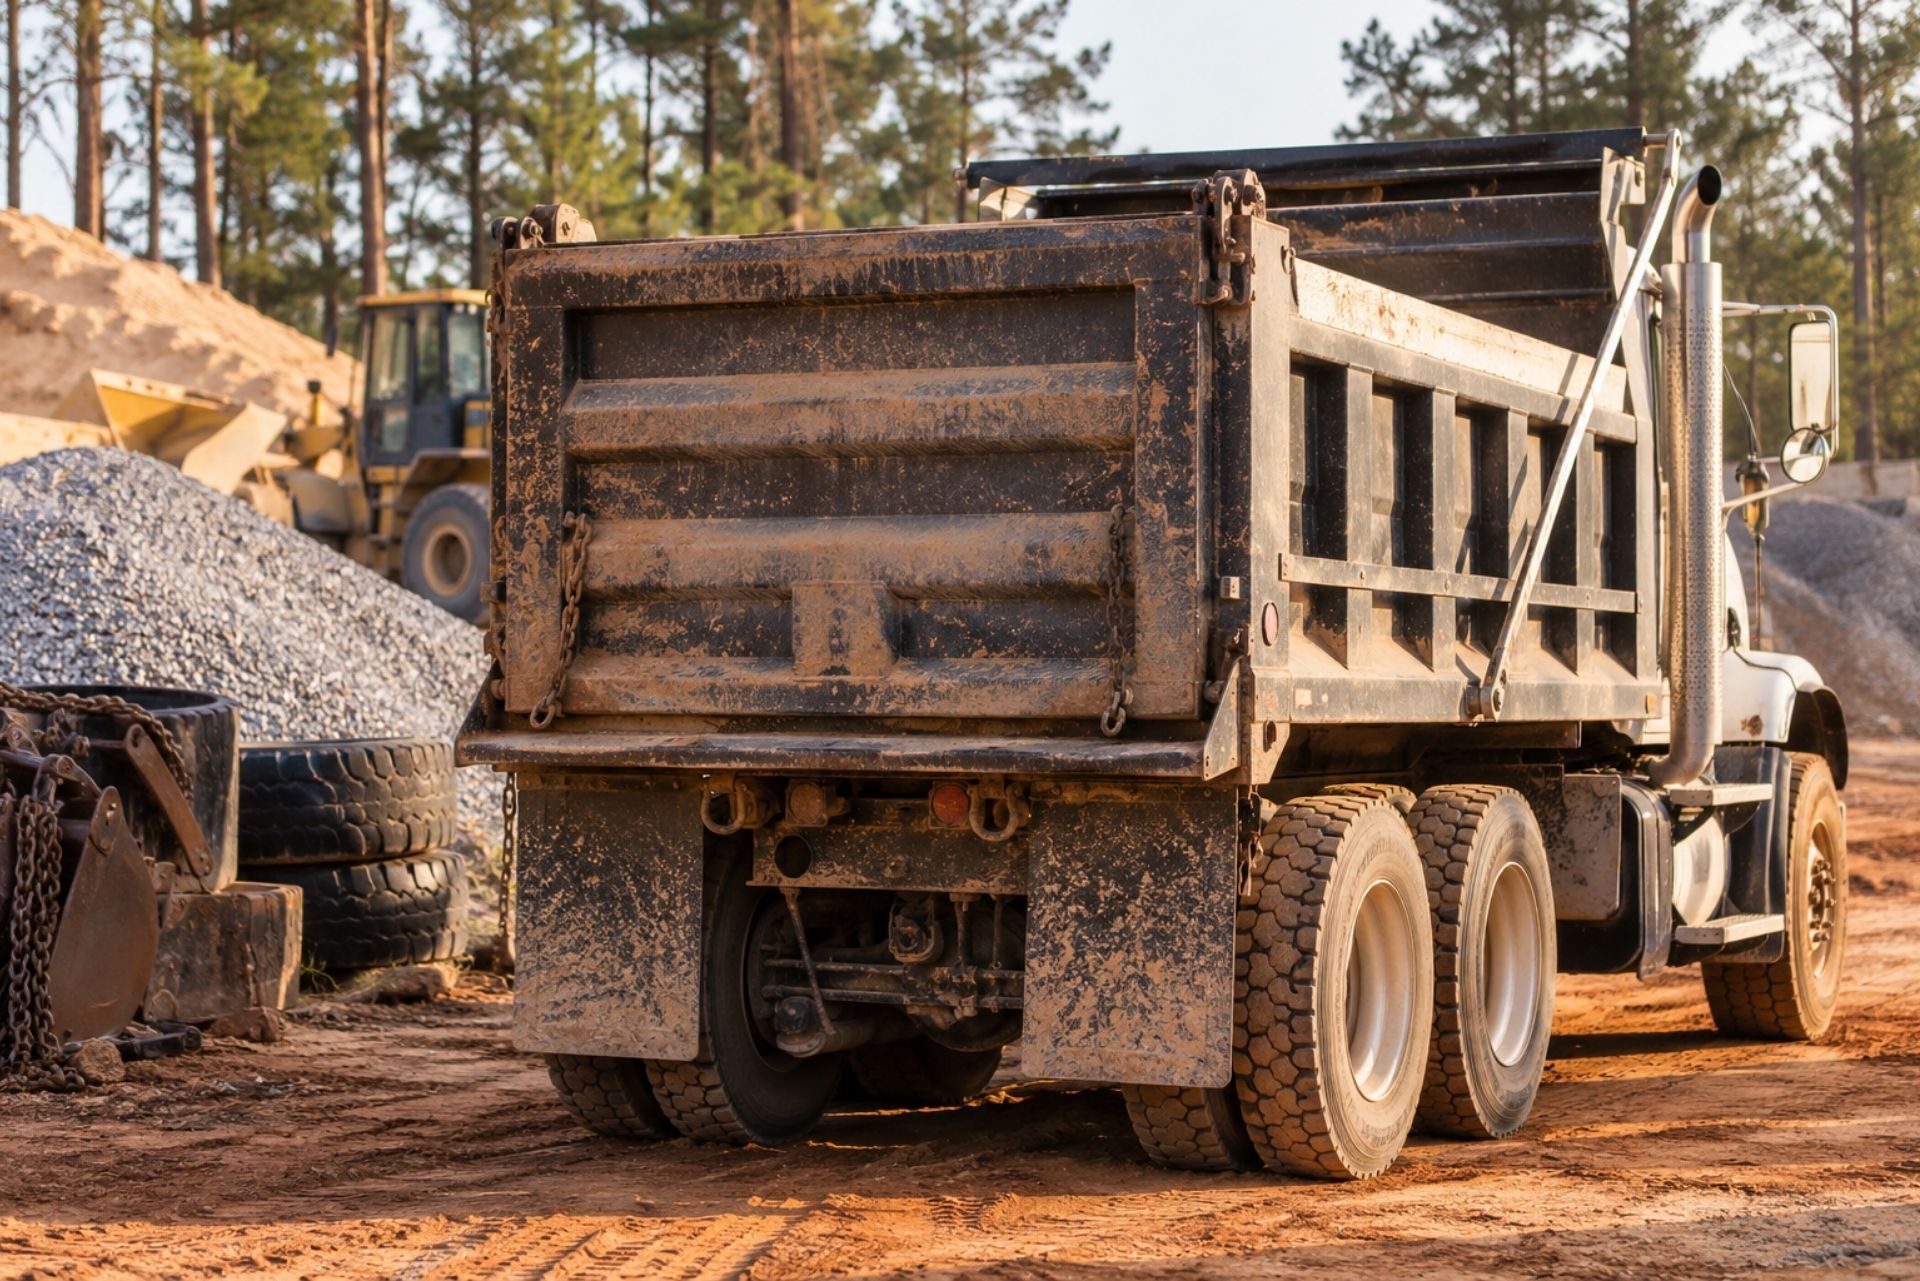
Physical damage coverage protects your trucks and equipment against collision, theft, vandalism, and weather events. For dump trucks, this is especially important because replacement costs are high: the cost for a new heavy-duty Class 8 tri-axle dump truck typically ranges from $250,000 to $300,000+ as of late 2026 (https://truecorecapital.com/blog/dump-truck-financing-2026/). Your policy should cover the actual cash value or agreed value of each unit, and you'll want to confirm that attached equipment like hydraulic systems and dump bodies is included.
Motor truck cargo coverage is a separate policy that protects the materials you're hauling. If a load of aggregate spills on the 405 or a pallet of construction materials shifts and damages a client's property, cargo coverage responds. Standard cargo policies don't cover pollution events, though. If you're hauling soil, asphalt, or anything with environmental exposure, you need a pollution liability endorsement added to your program.
General Liability vs. Professional Liability
General liability covers third-party bodily injury and property damage that happens away from your vehicle: think a worker dropping equipment at a job site or someone tripping over your staging area. It's separate from your auto liability, which only responds to incidents involving your trucks.
| Coverage Type | What It Covers | Typical Limits | Common Gaps |
|---|---|---|---|
| Auto Liability | Accidents involving your trucks | $750K - $1.2M+ | Doesn't cover job site incidents |
| General Liability | Third-party injury/damage at job sites | $1M/$2M | Excludes auto-related claims |
| Motor Truck Cargo | Damage to hauled materials | $100K baseline | Pollution events excluded unless endorsed |
| Hired & Non-Owned Auto | Vehicles you rent or employees' personal vehicles used for business | Matches primary auto limits | Often overlooked until a claim hits |
Standard vs. Specialized Hauling Coverage
Not all hauling operations carry the same risk profile, and your insurance should reflect that. A contractor moving clean fill between two local sites faces different exposure than an operator hauling demolition debris across county lines.
Standard commercial auto policies cover basic dump truck operations: local hauls of common materials like gravel, sand, and dirt within a defined radius. These policies work well for single-truck operators doing short runs for a handful of regular clients.
Specialized coverage becomes necessary when your operation involves hazardous materials, long-haul routes, oversized loads, or contractual requirements from general contractors. Many GCs now require $2 million in combined single-limit auto liability before they'll let you on site. If you're running transfer dumps or bottom dumps on
highway projects, your exposure profile is significantly different from a local fill hauler, and your premiums will reflect that. Annual all-in premiums for California dump trucks range from $12,000 to $18,000 for single-axle units and climb to $22,000 to $35,000 for transfer and end-dump configurations, with new authorities typically facing a 25 to 50 percent surcharge.
The Impact of AB5 and Regulatory Shifts on Your Coverage
The expiration of the AB5 exemption for construction trucking has forced a major reclassification across the industry. Owner-operators who previously worked as independent contractors now often fail the ABC test, meaning the hiring entity may be responsible for providing workers' compensation, auto liability, and other coverages for those drivers.
This shift has real insurance consequences. If you're a fleet owner using owner-operators, your insurer needs to know exactly how those relationships are structured. Misclassifying a driver as an independent contractor when they're legally an employee can void coverage on a claim. We've helped clients at Fusco Orsini & Associates restructure their driver agreements and insurance programs specifically to address this exposure.
The CARB Clean Truck Check program adds another compliance layer, with annual fees adjusted to $32.13 per vehicle for 2026. While it's not an insurance cost, non-compliance can affect your operating authority, which directly impacts your insurability.
California hauling insurance premiums aren't arbitrary. Underwriters evaluate a specific set of risk factors, and understanding them gives you real control over your costs.
Hauling Radius and Material Types
A truck that stays within a 50-mile radius of its home base carries less risk than one running 200-mile routes through urban corridors. Your hauling radius directly affects your premium because longer routes mean more highway exposure, more fatigue risk, and more jurisdictional complexity.
Material type matters just as much. Clean fill and gravel are low-risk commodities. Asphalt, contaminated soil, or construction debris with potential hazardous components trigger higher rates and may require specialized endorsements. Be honest with your agent about what you haul: if you tell your insurer you only carry sand and then a load of contaminated soil causes a spill, your claim will likely be denied.
Driver Safety Records and BIT Inspections
Your drivers' MVRs (motor vehicle records) are the single biggest factor in your premium calculation. A fleet with clean records and experienced drivers will pay significantly less than one with DUI histories or multiple at-fault accidents. California's Basic Inspection of Terminals (BIT) program also matters: a poor BIT inspection result signals to underwriters that your maintenance and safety practices are lacking.
Underwriters in 2026
increasingly view forward-facing dash cameras and telematics as mandatory rather than optional. In the 2026 underwriting environment, telematics data has shifted from an "optional perk" to a primary underwriting input (https://toofer.com/blog/fleet-telematics-commercial-auto-insurance-2026/), and these systems provide critical evidence in disputed claims. The trend toward nuclear verdicts in California trucking cases, where awards exceeding $10 million have become routine, makes this kind of documentation essential for your defense.
Frequently Asked Questions About Hauling Insurance
How much insurance does the state of California require for a dump truck? California for-hire property carriers with a GVWR of 10,001 lbs or more must maintain a minimum of $750,000 in liability insurance filed via Form MC 65 M (https://www.socaltruckins.com/what-truck-insurance-is-legally-required-in-california/), but that figure can rise to $1.2 million for bulk petroleum transporters (https://www.haulhandbook.com/california/trucking-insurance-requirements/). Many contracts require $1 million or $2 million, so carrying only the state minimum often isn't practical.
Does my personal auto policy cover my construction hauling? No. Personal auto policies specifically exclude commercial use and vehicles over a certain weight. If you use your personal truck for any hauling work, you need a commercial auto policy. A personal policy claim will be denied, and you'll be personally liable.
What is an MCP and why do I need one? A Motor Carrier Permit is required by the California DMV for anyone transporting property for compensation. Operating without one is illegal, and it's one of the first things CHP checks during roadside inspections. Your insurance must be on file with the DMV to maintain your MCP.
Are my trailers covered under the same policy? Trailers are typically covered for liability when attached to your truck, but they need to be specifically listed on your policy for full physical damage coverage. Detached trailers sitting at a yard or job site are often excluded unless scheduled separately.
Will my insurance cover a load that spills on the highway? Only if you carry motor truck cargo coverage with a pollution liability endorsement. A standard cargo policy covers damage to the load itself but won't pay for environmental cleanup, highway closure costs, or third-party contamination claims. These endorsements are inexpensive relative to the exposure they cover.
Making the Right Choice for Your Fleet
Your California dump truck insurance program should be built around your specific operation, not a generic template. The combination of fleet auto liability, physical damage, cargo protection, hired and non-owned auto coverage, and proper FMCSA filings creates a complete risk transfer strategy, but only when each piece is tailored to your hauling radius, materials, driver pool, and contractual obligations.
Premium increases have moderated to an 8 to 12 percent annual range for most California fleets as of mid-2026, but costs still climb for operators who don't actively manage their risk profile. Investing in telematics, maintaining clean driver records, and staying ahead of regulatory changes like the proposed FMCSA liability increases will keep your program competitive.
Start by auditing your current policies against the coverages outlined here. Look for gaps in cargo protection, verify your FMCSA and MCP filings are current, and confirm your driver classifications align with AB5 requirements. If you're unsure where you stand, the team at Fusco Orsini & Associates specializes in California construction hauling insurance and can walk through your program line by line. Don't wait for a claim to find out what's missing.
About The Author:
Michael Fusco
As CEO and Principal of Fusco Orsini & Associates, I’m dedicated to helping businesses and individuals achieve peace of mind through smarter insurance solutions. With extensive experience in commercial insurance and risk management, I focus on building long-term relationships and providing clarity, trust, and value in every policy we deliver.
// Coverage for Your Company
Protect Your Business, Employees, and Assets
We help business owners protect their companies from risks that can disrupt operations or threaten growth. Our team explains your options clearly and guides you to the right coverage for your business.
// Who We Help
Focused Insurance for Your Industry
We understand the unique risks and needs of different industries. Our team provides clear guidance and customized coverage to help you operate with confidence.
// Coverage for Individuals and Families
Protect What Matters Most at Home and Beyond
Renters Insurance
Affordable protection for your personal property in a rented space.
Life Insurance
Ensure your loved ones are financially secure when they need it most.
Umbrella Insurance
Extra liability coverage to protect you beyond standard policies.
// Frequently Asked Questions
Clear Answers to Common Questions

5.0 Reviews on Google
What You Need to Know Before Getting Started
People often ask us about the most common questions around business consulting, insurance, and employee benefits.
What types of insurance does my business need?
We evaluate your operations, identify risks, and explain the policies that make sense for your business. Our goal is to help you understand what you’re buying and ensure nothing important is overlooked.
The right coverage depends on your industry, size, and exposures. We’ll walk you through each option and help you make a confident decision.
Do you provide employee benefits?
Yes. Our dedicated benefits team offers group health, dental, vision, life, and disability plans. We also help employees with claims and explain how to use their benefits effectively.
We design plans that meet your company’s goals while keeping costs manageable and ensuring employees feel supported.
Do you only serve clients in California?
No. While we are based in San Diego, California, we work with clients in 31 states across the country.
We have the licenses and experience to support businesses of all sizes wherever they operate.
Can you review my existing policies?
Absolutely. We offer policy reviews at no cost to you. We’ll look for gaps in coverage, overlapping policies, and opportunities to save money.
Our team makes transitioning from your current provider simple and seamless.
How quickly can I get a quote?
In most cases, we respond the same business day with clear options and next steps.
We know that time matters, and we work efficiently to provide you with answers and coverage without unnecessary delays.
// What Our Clients Say
Reviews from Business Owners Like You
Over 500 Five-Star Ratings Across Platforms
// Business Tips & Resources
Helpful Articles for Business Owners
Our blog offers clear advice to help you protect your business, support your employees, and plan for the future with confidence.
Contact Us
Phone
Location