
What’s Covered in a Workers Compensation Policy?
See How We're Different
or call us: (858) 384‑1506
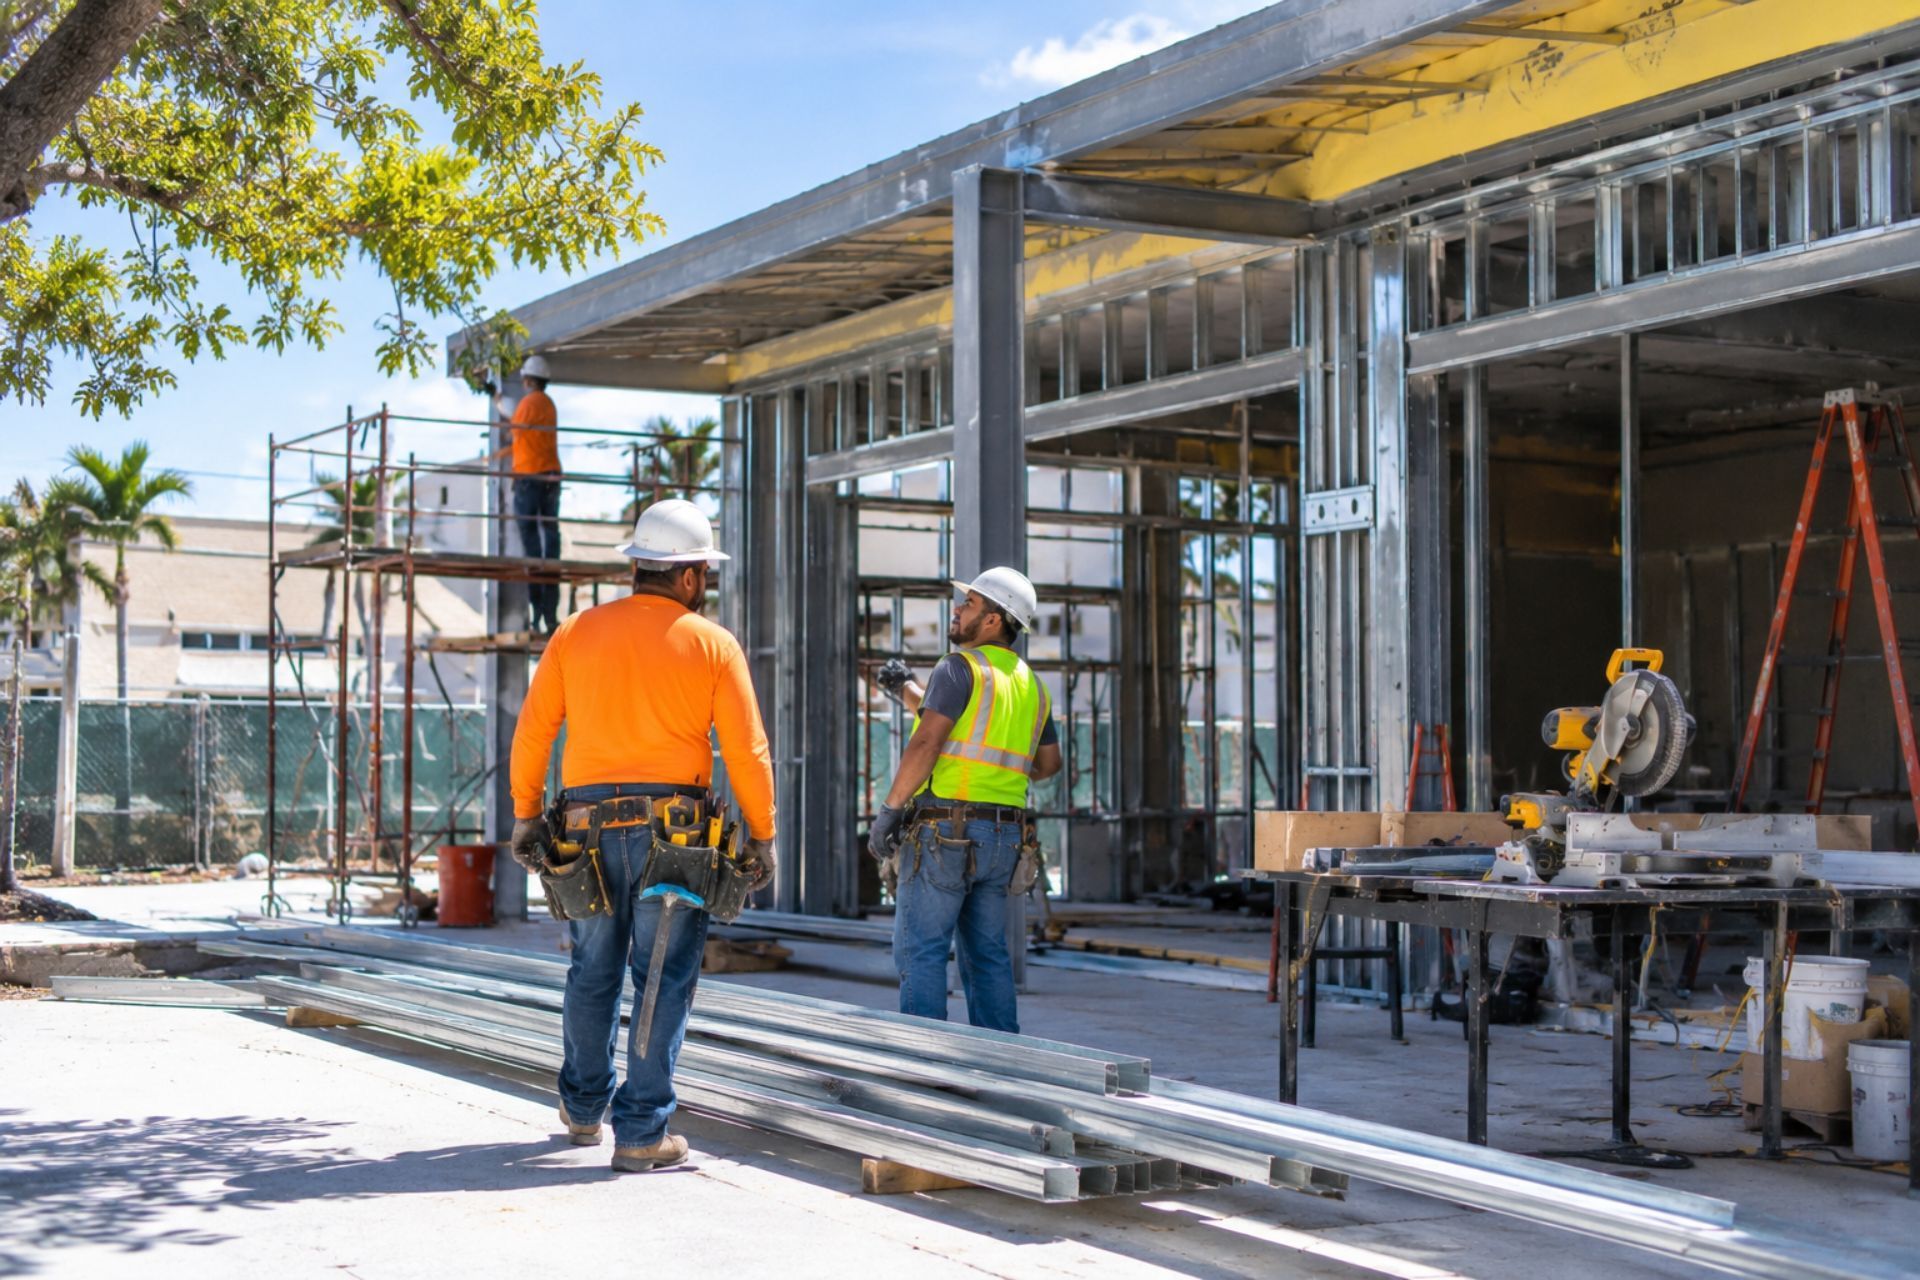
If you own a construction company and have a California-based business, this post is for you. Workers compensation is critically important when it comes to the construction industry because of the physical risk inherent in the profession. You (or your employees) are lifting things. There may be strain on the muscles and ligaments. There could be an accident. You know you need it and it’s required by law. But what’s covered in a workers compensation policy?
Workers compensation is an insurance policy that helps to protect your assets in the event that one of your employees is hurt on the job.
What’s covered in a workers comp policy?
When your employee is injured on the job, the policy provides them with financial support to cover medical expenses and lost wages.
Medical coverage + wage replacement =”indemnity”
Only injuries that arise out of and in the normal course of business are reimbursed. Medical coverage may include physician visits, prescription medications, surgeries, etc. The amount to cover lost wages is based on the employee’s weekly wage as determined by California law.
What’s not covered?
The key to workers compensation is that the injury must be work-related. If an employee gets hurt offsite on their lunch break, that typically doesn’t fall under their coverage. If you are commuting to your regular workplace, an injury is likely not covered but if you’re traveling to another job site during work hours, then it usually would be. Employees may also be denied coverage for self-inflicted injuries or if the employee was committing a crime.
Protect yourself from unexpected financial burdens by setting up your business with workers comp insurance. If you’re interested in getting a quote on a policy or if you have any lingering questions about what is or is not covered, schedule a call with us.
Recent Post